Compare Bank Home Loan Offers — Pakistan
Every field, the formula behind it, and a worked example.
Last updated:
Help › The calculators › Compare three banks
Three offers side by side, with the fees included. The cheapest bank is not always the one with the lowest rate.
 Open this calculator
01
When to use it
After you have asked three banks and written down what each one said. Not before — this calculator has nothing to compare until you do.
02
Every field, explained
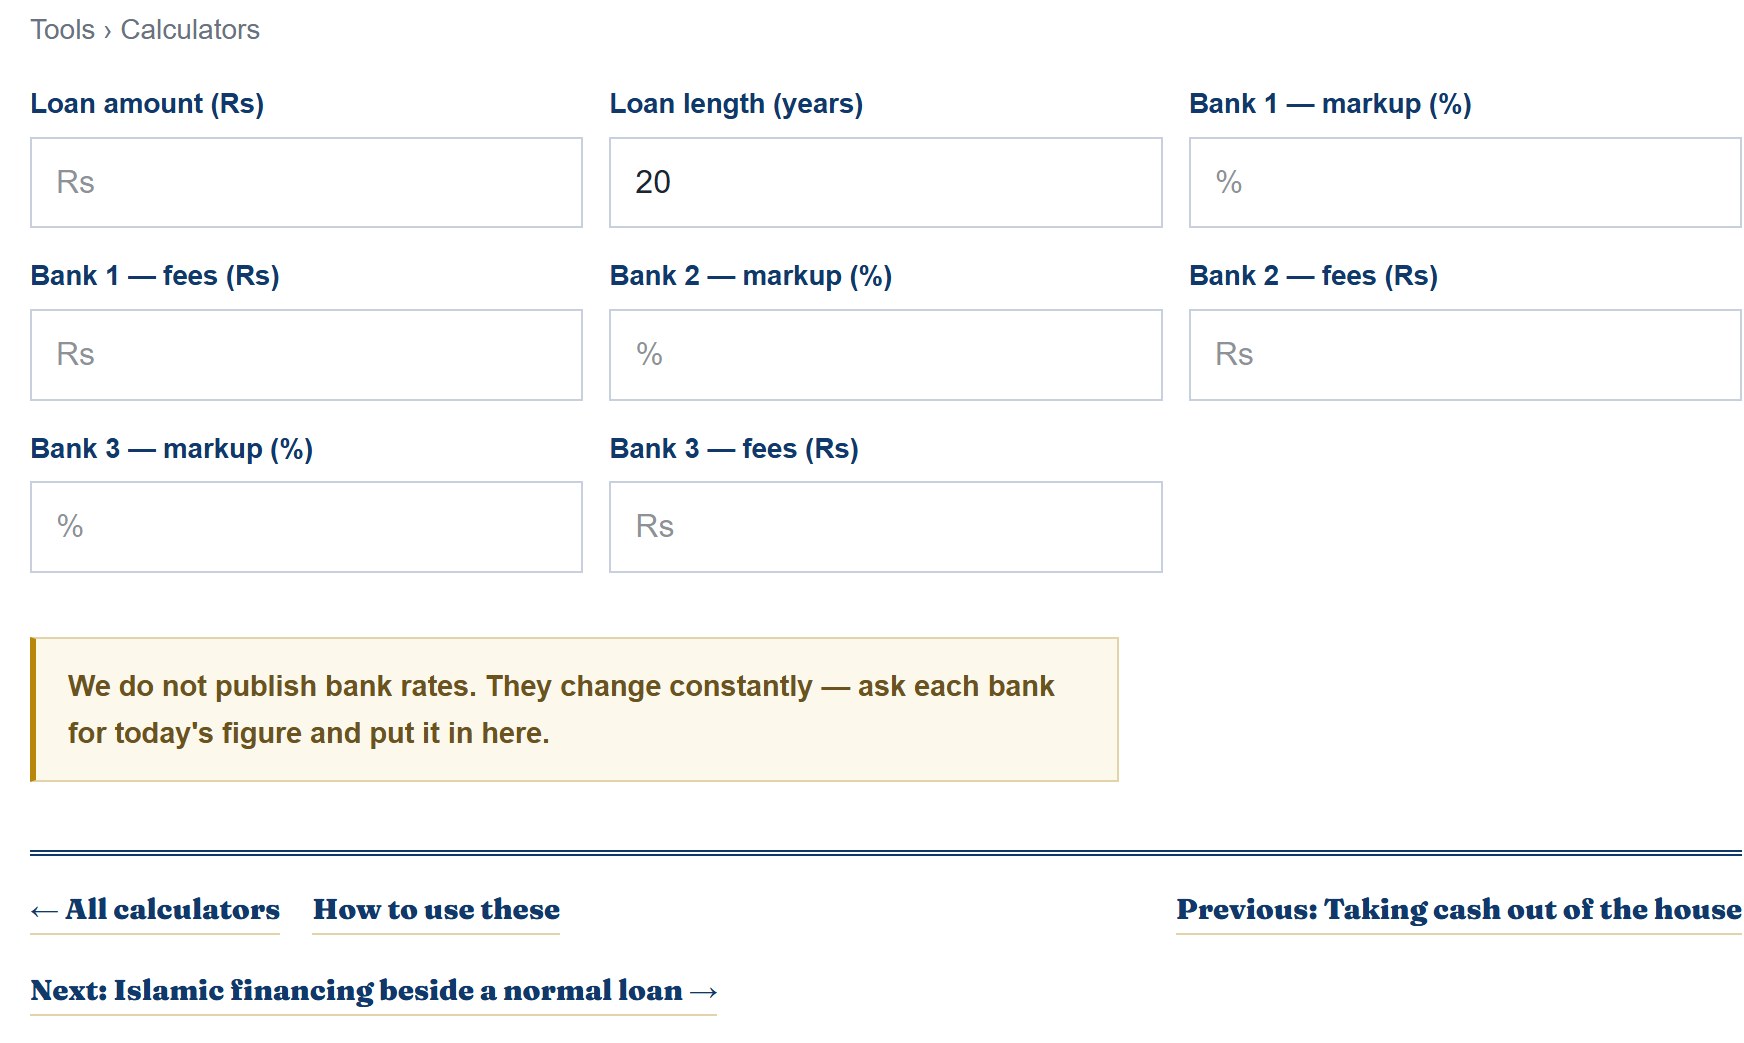
| Loan amount (Rs) | The same loan for all three, or the comparison is meaningless. |
| Loan length (years) | Also the same for all three. |
| Bank 1 — markup (%) | What that bank quoted you, today. |
| Bank 1 — fees (Rs) | Processing, valuation, legal, documentation — everything they charge once at the start. |
| Bank 2 — markup and fees | The same two boxes for the second offer. |
| Bank 3 — markup and fees | And the third. Leave a pair empty if you only have two offers. |
03
How the answer is worked out
- For each bank, the monthly instalment is worked out on the same loan and the same term at that bank's markup.
- The lifetime cost is the instalment times the number of months, plus that bank's one-time fees.
- The bank with the lowest lifetime cost is named at the top. The table shows all three so you can see how close the race was.
A worked example — Rs 1 crore over 20 years
| Bank 1 | 19.5%, fees Rs 1.5 lakh |
| Bank 2 | 20%, fees nil |
| Bank 3 | 19%, fees Rs 5 lakh |
Bank 3 has the lowest rate but its fees wipe the advantage out; Bank 1 wins. On a long loan a half-point usually beats a fee, but not always — which is exactly why you put both in.
04
Mistakes people make
- Comparing offers at different terms or different loan amounts.
- Leaving the fees empty because "they said it is small". Ask for the figure.
- Choosing on the instalment alone. The instalment is monthly; the fee is upfront; only the lifetime cost puts them on the same footing.
- Forgetting to ask whether the rate is fixed or floating — a low floating rate can rise next year.
05
What it does not do
- We do not publish bank rates. They change constantly and vary by customer. Everything here comes from what the banks told you.
- It assumes all three rates stay fixed for the whole term.
- It does not judge service, speed or how a bank behaves when you are late.
06
Questions
- Why don't you list the banks' rates yourself?
- What if I only have two offers?
Because a rate we published last month could cost you lakhs this month. Every bank quotes differently to different customers anyway — the only rate that matters is the one they gave you.
Leave the third pair of boxes empty. Two is already better than one.