Home Loan Instalment Calculator — DHA Lahore
Every field, the formula behind it, and a worked example.
Last updated:
Help › The calculators › Bank instalment
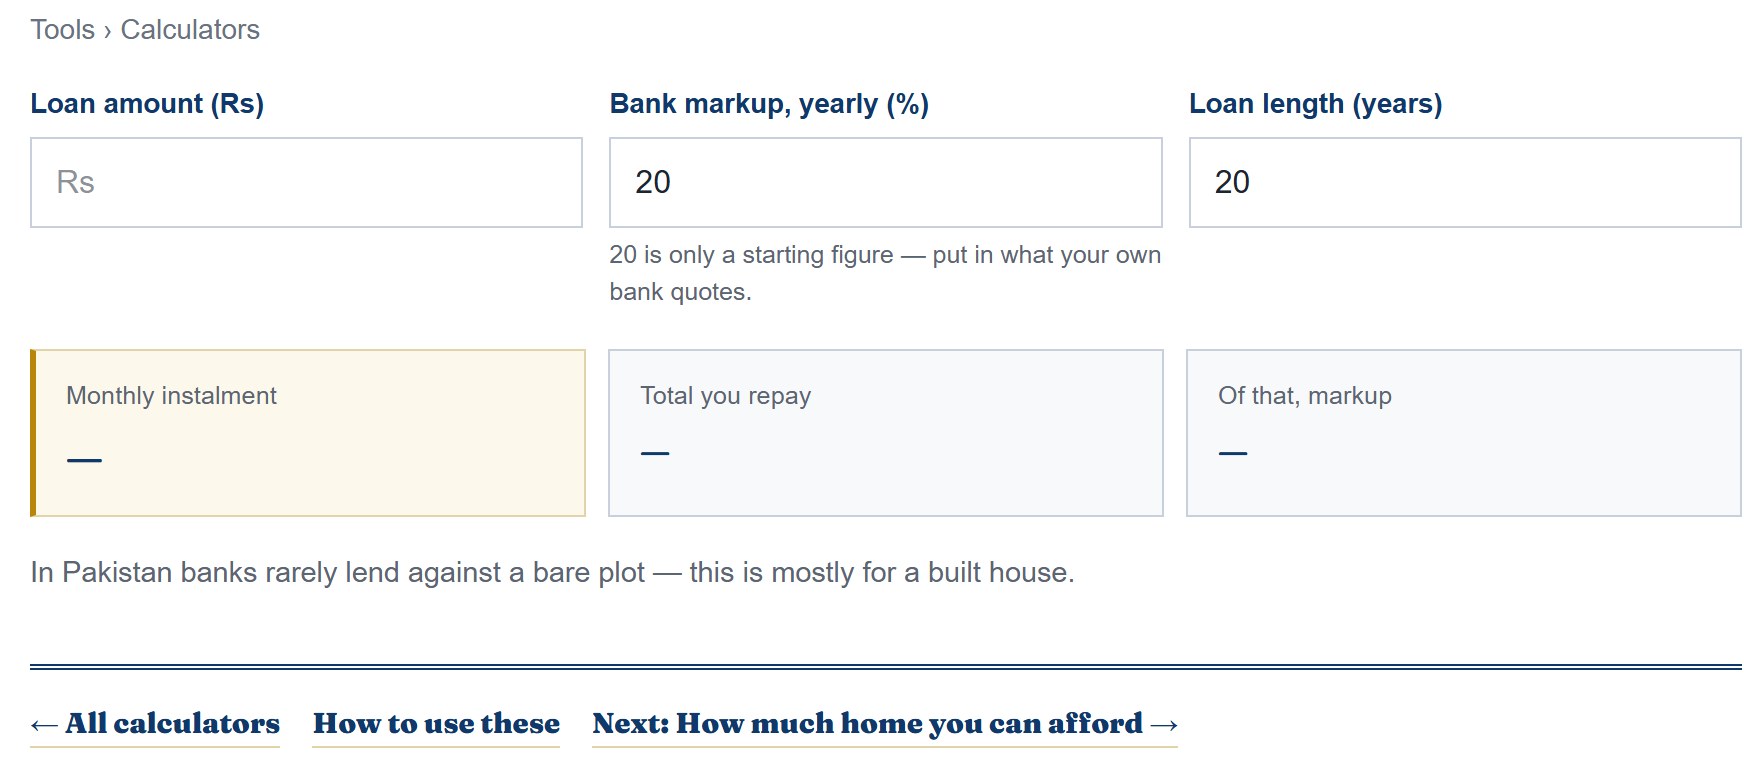
Three boxes, four answers: what you pay each month, what you pay in all, how much of that is the bank's markup rather than the house, and how long half the loan takes to clear — with a line underneath showing what is still owed at the end of every year.
 Open this calculator
01
When to use it
The moment a bank quotes you a rate. It is also the fastest way to see why a longer loan is not the bargain it looks like.
02
Every field, explained
| Loan amount (Rs) | What you are borrowing — the price minus your down payment, not the price itself. |
| Bank markup, yearly (%) | It starts at 20 because that is a common figure in Pakistan today. It is only a starting figure — replace it with what your own bank quotes you. |
| Loan length (years) | How long you keep paying. Longer means a smaller instalment and a much larger total. |
03
How the answer is worked out
- The yearly markup is divided by twelve to get a monthly rate, and the years are multiplied by twelve to get the number of instalments.
- The standard instalment formula is then applied: loan × rate ÷ (1 − (1 + rate)−months). Every instalment is the same size; what changes is how much of it is markup.
- Total repaid is simply the instalment multiplied by the number of months, and the markup is that total minus the loan.
- The line underneath is worked out month by month: every instalment first pays that month's markup, and only what is left comes off the loan. That is why the line hardly moves in the early years — and why half the loan is often still owed long past the halfway year.
A worked example
| Loan | Rs 1 crore |
| Markup | 20% a year |
| Length | 20 years |
| Monthly instalment | Rs 1.7 lakh |
You repay about Rs 4.08 crore in all — Rs 3.08 crore of it markup. On the same loan over 10 years the instalment rises to roughly Rs 1.93 lakh but the total falls to about Rs 2.32 crore. The shorter loan costs Rs 76 lakh less.
04
Mistakes people make
- Entering the property price instead of the loan. Take your down payment off first.
- Leaving the markup at 20% without asking a bank. Two points moves the instalment by thousands a month.
- Choosing the longest term because the instalment looks comfortable, without looking at the total underneath it.
- Forgetting that transfer cost and taxes are on top of all of this.
05
What it does not do
- It is not an approval, and it does not know whether a bank will lend on this property at all.
- It assumes the markup never changes. In Pakistan most home loans are variable.
- It does not include the bank's processing fee, insurance or valuation charges.
- In Pakistan banks rarely lend against a bare plot — this is mostly for a built house.
06
Questions
- Why is the total so much bigger than the loan?
- Does the instalment change over time?
- Is my data sent anywhere?
Because markup is charged every month on whatever is still owed. Over twenty years that adds up to more than the house. It is the single strongest argument for a shorter term or a bigger down payment.
Here, no — the calculation assumes a fixed markup. A real Pakistani home loan usually moves with KIBOR, so your instalment will move too.
No. Every calculator on this site runs inside your own browser.