Refinance Calculator — should you move your home loan
Every field, the formula behind it, and a worked example.
Last updated:
Help › The calculators › Is refinancing worth it
A lower rate saves you money every month, but switching costs money once. This works out when the one pays for the other.
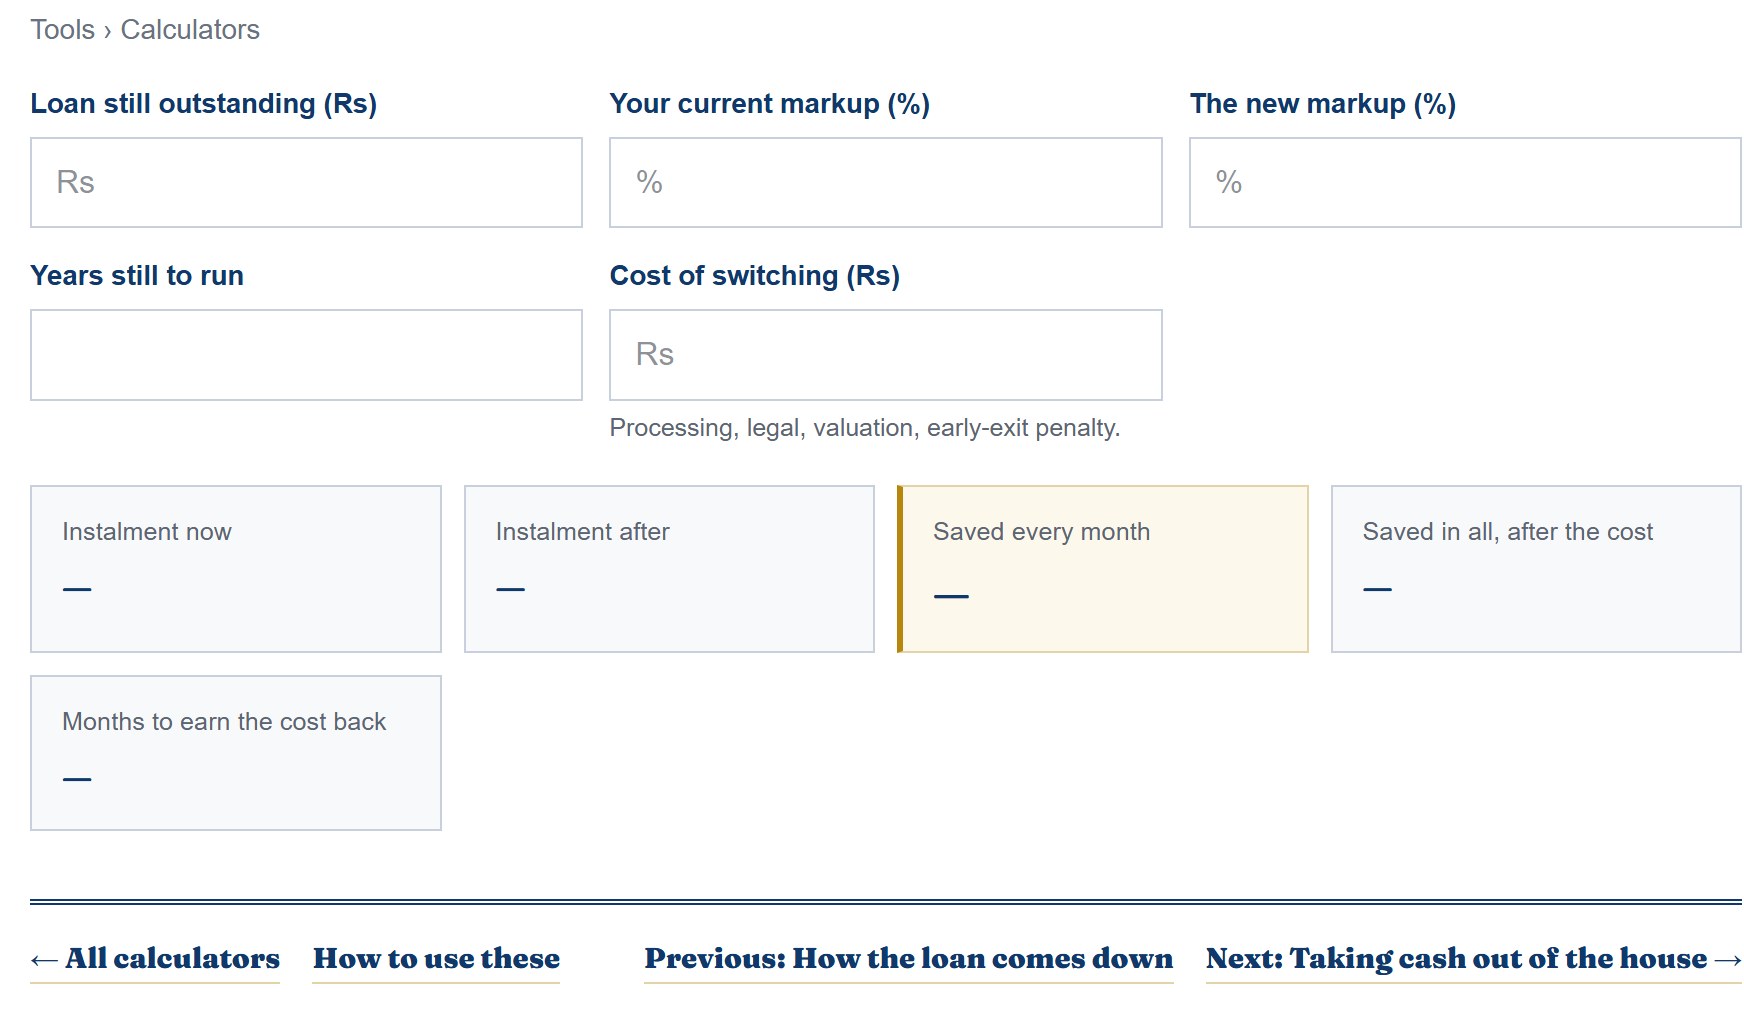 Open this calculator
01
When to use it
When another bank offers you a better rate, or when rates fall and your own bank has not passed it on.
02
Every field, explained
| Loan still outstanding (Rs) | Not the original loan — what you still owe today. Your bank's statement has it. |
| Your current markup (%) | What you are paying now. |
| The new markup (%) | What the other bank is offering. |
| Years still to run | How long is left on the current loan. Keep the new loan the same length, or the saving is an illusion. |
| Cost of switching (Rs) | Processing, legal, valuation and — the one people forget — your current bank's early-exit penalty. |
03
How the answer is worked out
- The instalment is worked out twice on the same outstanding balance and the same remaining years: once at the old markup, once at the new one.
- The difference is your monthly saving. Multiplied across the remaining months and minus the switching cost, that is the real saving.
- The switching cost divided by the monthly saving gives the number of months before you are actually ahead.
A worked example
| Outstanding | Rs 80 lakh |
| Now / offered | 22% / 18% |
| Years left | 12 |
| Cost of switching | Rs 2 lakh |
| Monthly saving | about Rs 21,000 |
You are ahead after about 10 months, and about Rs 28 lakh better off over the remaining twelve years. If you plan to sell in a year, it is not worth it.
04
Mistakes people make
- Stretching the new loan back out to twenty years. The instalment drops, but you pay far more in the end — that is not a saving.
- Leaving the switching cost empty. The early-exit penalty is often the biggest part of it.
- Comparing against the original loan instead of what is still outstanding.
05
What it does not do
- It does not know your bank's penalty — ask for it in writing.
- It assumes both rates stay fixed. If your current loan is variable, the gap may close on its own.
- It does not account for the weeks of paperwork a switch takes.
06
Questions
- How big a rate drop makes it worth switching?
- Does the calculator include the new bank's fees?
There is no fixed rule — it depends on the balance, the years left and the cost. Put in the real numbers; if the break-even is longer than you plan to keep the house, the answer is no.
Only if you put them into the switching-cost box. Ask for a full list; there is usually more than one line.